1 min read
Landlords: how rental income is taxed
Rent minus allowable costs is your taxable property profit. Mortgage interest follows its own rule, and letting a room in your home may be tax-free.
In short
If you let out property, your rental profit is added to your other income and taxed at your Income Tax rates. Profit is rent minus allowable running costs. You report it on the property pages of your Self Assessment return.
How it works
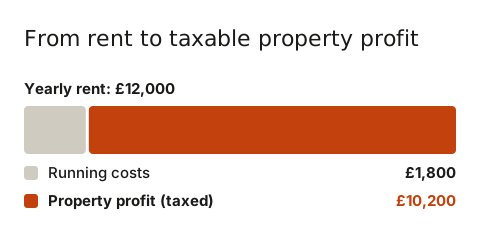
Typical allowable costs include letting agent fees, landlord insurance, repairs and maintenance, bills you pay for the tenant, ground rent and service charges, accountancy fees, and replacing furnishings like-for-like.
Mortgage interest is the big exception for individual landlords of residential property. Rather than deducting it as a cost, you currently get a tax reduction linked to the basic rate. This has been a significant change for higher-rate landlords. It's a policy area that changes, so check GOV.UK for how it works now.
Other things to know:
- Property allowance: a small tax-free amount of property income. Below it you may not need to report. Above it you can use it instead of actual costs.
- Rent a Room: letting a furnished room in your own home can be tax-free up to a set yearly amount.
- Jointly owned property: income is usually split between owners.
- Selling later: a gain on a property that wasn't your home may mean Capital Gains Tax.
An example
Using made-up figures: Mark lets a flat for £12,000 a year. Agent fees, insurance and repairs come to £1,800, so his property profit is £10,200. His mortgage interest isn't deducted from that figure. Instead, it reduces his tax bill when the return is worked out.
Common mistakes
- Deducting full mortgage repayments, including capital. Only interest counts, and that's through its own rule.
- Claiming improvements as repairs. See Repairs vs improvements.
- Forgetting Making Tax Digital counts property income too.
Your next step: list last year's rent and every property cost, separating mortgage interest from everything else.